
AI Education
AI EDUCATION: What Is a Data Mart?
By Christopher Robbins · Oct 22, 2026 Views: 1,687
Each week we find a new topic for our readers to learn about in our AI Education column.
Finding a needle in the haystack is no longer enough.
Today, we need to be able to map out the entire haystack, straw by straw, understanding each straw individually and in relation to each other individual straw and the structure of the haystack itself.
Welcome to AI Education, where we're talking about data again, in case you couldn't tell, the haystack is our data. The information we potentially have access to. The problem we're faced with, in a traditional sense, is that to understand what's going on with our haystack without powerful technology in our hands, we'd pretty much need to tear it apart.
Financial institutions have accumulated enormous quantities of data about customers, transactions, investments, markets, employees, operations and risks. Unfortunately, collecting information is not the same as making it useful. Much of that data remains scattered across databases, applications, departments and legacy systems—different haystacks—complicating the efforts of financial professionals and increasingly sophisticated AI applications to extract meaningful insights.
Luckily, with our data, we have different architectures and operational systems that can help us virtually pick apart the haystacks without destroying the structures, or the data, as a whole, and we're going to talk about one of those technologies today: The data mart.
What Is a Data Mart?
A data mart is a specialized repository of information organized around a particular business function, subject, department or group of users. It typically contains a carefully selected subset of information from a larger enterprise data warehouse, although it can also draw directly from operational databases, external sources or a combination of systems.
Data marts help organizations organize large collections of information into smaller, more manageable, purpose-built repositories designed to answer particular business questions. For financial institutions, they can make the difference between an AI application that spends its time searching through inconsistent records and one that rapidly accesses reliable information about investment portfolios, credit exposures, customer relationships or financial performance. Although data marts predate modern machine learning and generative AI, their underlying purpose aligns with one of the central challenges facing enterprise AI adoption: delivering the right information, in the right format, to the right user or application at the right time.
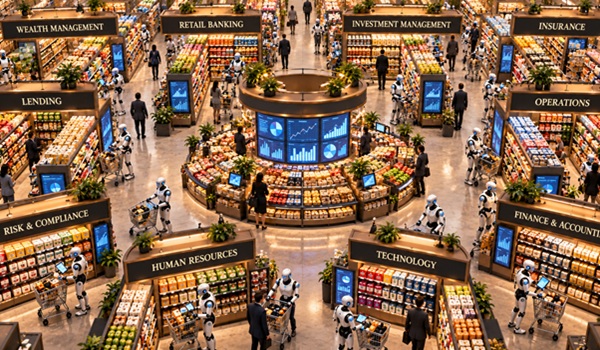
The simplest way to understand a data mart is to imagine a large financial institution's information infrastructure as a supermarket. The enterprise data warehouse is the entire store, containing merchandise across numerous departments. A data mart is more like a specialized counter offering a curated selection of products to customers with particular needs. Someone shopping for fresh seafood does not need to navigate the entire supermarket to find it.Similarly, a financial advisor interested in portfolio performance does not necessarily need access to the institution's human resources records, corporate procurement information or marketing campaign data. A portfolio management data mart can provide the relevant holdings, valuations, returns, benchmarks and client-account information in a structure designed specifically for investment analysis.
Properly implemented, a data mart incorporates business definitions, data transformations, access controls and relationships among datasets. It is designed to make information understandable and reusable, rather than merely accessible. It need not be a separate physical database. Modern data marts can exist as logical views, materialized tables, dedicated schemas or specialized analytical environments within larger cloud data platforms. Their defining characteristic is their business purpose, not necessarily their physical location.
Who Are Data Marts For?
Data marts serve business analysts, financial professionals, executives, data scientists and increasingly AI-powered applications. Their usefulness stems from their ability to organize information according to how a particular group actually works. A corporate finance department might maintain a data mart containing revenues, expenses, budgets, forecasts and profitability measures. Financial planning and analysis teams can use it to compare actual results with expectations, investigate cost overruns and produce management reports. Chief financial officers can use dashboards connected to the same repository to monitor performance across business units.
Marketing departments might use data marts to consolidate campaign spending, customer acquisition costs, conversion rates and engagement measures. Sales organizations can organize prospect records, pipeline activity and revenue performance around common reporting definitions.
Within financial services, the applications become more specialized. A commercial bank's lending division might maintain a credit data mart containing borrower characteristics, loan balances, collateral values, repayment histories, delinquency rates and credit risk indicators. Risk managers could analyze that information to identify deteriorating loan portfolios or emerging concentrations. An investment management firm could maintain a performance data mart containing securities holdings, transactions, cash flows, benchmarks and historical returns. Portfolio managers and investment analysts could use it to evaluate performance attribution, assess exposures and compare investment strategies.
Characteristics of Data Marts
The defining characteristic of a data mart is its subject-oriented design. Rather than attempting to represent an entire organization, it focuses on a particular domain, such as credit risk, customer profitability, investment performance or regulatory reporting. This specialization can make information easier to understand. Tables, metrics and relationships are organized according to the terminology and workflows of the intended users. A portfolio manager should not need extensive knowledge of the institution's database infrastructure to determine the performance of a particular investment strategy.
Another characteristic is the use of structured, curated information. Data marts typically contain data that has undergone some combination of extraction, cleaning, standardization, transformation and aggregation. These processes make information more consistent and useful for analysis.
Performance is another potential advantage. Because a data mart generally contains fewer subjects and may include precomputed metrics, frequently requested reports can run faster than complex queries against larger repositories. However, a smaller data mart is not automatically faster; query design, indexing, storage architecture and available computing resources also matter.
Data marts can improve accessibility by giving business users a relatively straightforward analytical environment. They can also improve security by restricting access to particular categories of information, provided that authorization policies and controls are properly configured. Implementation may be less demanding than building an enterprise-wide data warehouse from scratch. Organizations can address an immediate business need without waiting for every department's information to be consolidated. IBM identifies faster implementation, easier maintenance and improved analytical efficiency among the principal benefits.
Data Marts Versus Data Warehouses, Data Lakes and Lakehouses
To understand the place of data marts in modern information technology, it is useful to distinguish them from three related architectures: data warehouses, data lakes and data lakehouses. A data warehouse is a centralized repository that consolidates information from multiple operational systems and organizes it for enterprise-wide analysis. It typically contains historical, structured and standardized information covering numerous business functions.
A data mart, by comparison, is narrower. Where a warehouse might contain an entire financial institution's customer, accounting, lending and investment records, a data mart might contain only the information needed to analyze mortgage profitability. The difference is fundamentally one of scope and purpose, rather than a strict limit on storage capacity.
A data lake takes a different approach. Instead of requiring information to be extensively organized before storage, it accommodates large quantities of raw structured, semi-structured and unstructured data. A financial institution's lake might contain transaction records alongside emails, call recordings, scanned documents, market feeds and customer communications. This flexibility makes data lakes particularly valuable for exploratory analytics and machine learning, although raw information often requires substantial preparation before it becomes suitable for routine business reporting.
A data lakehouse combines elements of the lake and warehouse approaches, enabling organizations to retain flexible storage while adding capabilities for structured queries, governance and analytical processing.
These architectures are not mutually exclusive. A financial institution might collect information in a data lake, standardize it within a warehouse or lakehouse, and publish specialized data marts for different departments.
The Three Principal Types of Data Marts
Data marts are generally classified as dependent, independent or hybrid, based on where their information originates. A dependent data mart draws information from a central enterprise data warehouse. The warehouse performs much of the integration and standardization, while the mart presents a specialized selection to its intended users. This approach helps preserve consistent definitions across departments. A bank's credit risk and finance teams, for example, could access different subsets of a common warehouse while relying on shared loan identifiers and accounting classifications.
An independent data mart draws information directly from operational systems or external sources without depending on a central warehouse. It can be attractive to organizations seeking to address a particular analytical need quickly, especially when enterprise infrastructure is unavailable or inadequate. However, independent marts are more likely to introduce inconsistent definitions, duplicated information and fragmented governance.
A hybrid data mart combines centrally governed warehouse information with additional operational or external datasets. An investment firm might supplement internal portfolio information with market prices, benchmark data or third-party research. Hybrid architectures offer flexibility but require careful reconciliation of data sources.
What Do Data Marts Have to Do With Artificial Intelligence?
Data marts have become increasingly relevant to AI because sophisticated models require more than enormous quantities of information. They require information that is appropriate, consistent, accessible and meaningful for a particular task. A machine learning model designed to predict loan defaults, for example, needs relevant historical lending data, reliable outcome labels and clearly defined borrower characteristics. Providing it with an entire bank's unfiltered data infrastructure would introduce unnecessary complexity. A specialized credit data mart can supply curated records containing repayment histories, loan characteristics, risk indicators and other permissible predictive variables.
Data marts can support feature engineering, the process of developing variables that machine learning algorithms use to identify patterns and make predictions. They can also provide historical datasets for model training, validation and performance monitoring. However, a data mart is not automatically a feature store. A dedicated feature store generally adds capabilities for managing reusable machine learning features, including consistent training and inference definitions and, where required, low-latency online access.
The relationship extends to generative AI.
A financial services chatbot or AI agent might need to answer questions about revenues, account balances, portfolio performance or operational efficiency. Instead of searching unrestricted enterprise databases, the system could retrieve information from an authorized data mart containing certified business metrics. This approach can improve relevance, reduce unnecessary data exposure and simplify the process of generating defensible answers. Nevertheless, curated data does not eliminate hallucinations or guarantee correct AI reasoning. Models can still misinterpret questions, apply inappropriate calculations or invent conclusions.
Data Marts in Financial Services
Financial institutions are particularly well suited to data marts because their operations involve numerous specialized information domains, each with distinct analytical requirements. Banks can use data marts for credit risk, liquidity management, capital planning, profitability analysis, customer segmentation and regulatory reporting. Insurers can use them for underwriting, claims analysis, actuarial modeling and fraud detection. Investment firms can create specialized repositories for securities research, performance attribution, trading activity, portfolio construction and risk management.
Financial planning departments can consolidate information from enterprise resource planning systems, payroll applications and spreadsheets to support budgeting and forecasting. For example, Profitbase's Finance Datamart illustrates how a finance-focused repository can organize financial information around reporting, planning and management requirements.
In wealth management, the potential applications are especially compelling. Consider a registered investment advisor seeking to evaluate the profitability of its client relationships. Relevant information might reside in portfolio accounting software, customer relationship management systems, billing platforms and financial planning applications. A client profitability data mart could combine authorized information from these systems, enabling the firm to compare advisory revenues, assets under management, service activity and operating costs. An AI application could then analyze the prepared information to identify patterns in service delivery or recommend operational improvements. A separate portfolio analytics mart might support performance reporting, tax-loss harvesting analysis, asset allocation monitoring and investment risk assessment.