
News/Commentary
LOOKING BACK | Is AI the Next NFT or Metaverse?
By DWN Staff · Oct 22, 2026 Views: 1,989
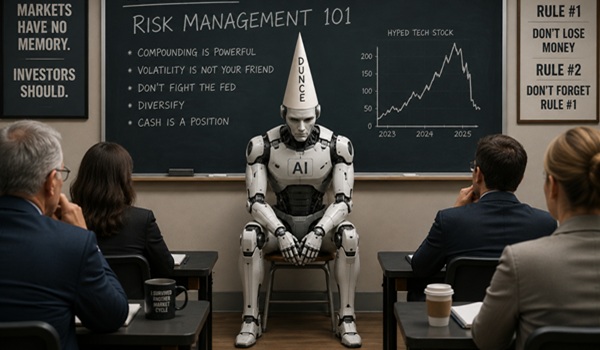
Let's say it even louder for the people in the back: We love being wrong.
And it's a good thing, too, because we're often wrong. But in the case of technologies like non-fungible tokens (NFTs) and the metaverse, we're not quite wrong. We did enthusiastically cover the rise of the metaverse and NFTs, but we were never really sold on them. For one thing, while we can still acknowledge that NFTs have a whiff of utility about them, that utility never to us seemed like a big deal. At least, not a big enough deal for us to want to own or use a NFT.
The metaverse reminded us too much of Second Life. Back in our non-traditional college days, we had an entire political science course that unfolded as a project on Second Life, a platform that the university had apparently made some kind of investment in, building it's own Second Life space including digital representations of on-campus architecture. It was neat, as part of the course, we were encouraged to explore Second Life, interact with people and explain what we had seen.
The problem was that there weren't really any people on Second Life at that point. What has become online law, that if you build a free and open space on the internet it will eventually be dominated by people and/or bots who are only there to try to screw each other—either through porn, cybersex, computer viruses or scams—or some combination of all of them, and Second Life was no different. We were supposed to be there to learn, but there was no there there.
To us, the metaverse was just Second Life on steroids.
The technology industry has a peculiar habit of declaring the future before determining whether anybody wants to live in it. During the past two decades, investors, technology executives and corporate strategists have been promised revolutions in virtual reality, augmented reality, blockchain, digital ownership, immersive entertainment and virtual commerce. Some of those technologies have become useful, even indispensable, in specialized applications. Others have produced spectacular financial losses, disappointed consumers and quietly disappeared from corporate strategic plans. Today, artificial intelligence is receiving the capital, attention and extravagant predictions once lavished on the metaverse and NFTs. The comparison raises uncomfortable questions for financial institutions and investors: Is AI fundamentally different from those earlier technological disappointments? Can genuinely useful innovations coexist with speculative bubbles? And how can businesses distinguish a technology with lasting commercial value from an expensive solution searching for a problem?
Where Did the Metaverse Go?
Few corporate transformations have been as conspicuous as Facebook's October 2021 decision to rename itself Meta Platforms. CEO Mark Zuckerberg envisioned a successor to the mobile internet: a network of persistent, interconnected, immersive digital environments in which people would socialize, work, shop, play and conduct business through virtual representations of themselves.
The metaverse was supposed to become an entirely new computing platform. Virtual offices would replace video meetings. Digital storefronts would create new retail opportunities. Companies would purchase virtual property, consumers would acquire digital clothing, and financial institutions would eventually provide payments, lending and wealth management services inside virtual worlds. For a time, the enthusiasm was extraordinary. Microsoft, Nvidia, Roblox, Epic Games and numerous startups promoted different visions of virtual environments, while consulting firms produced ambitious forecasts of their potential economic value. Yet the commercial revolution never materialized.
Meta's Horizon Worlds struggled to become a mainstream destination, and consumers showed limited interest in spending hours inside virtual environments wearing cumbersome headsets. Businesses discovered that ordinary videoconferencing, messaging and collaboration software often accomplished the same tasks more cheaply and conveniently. The economics were equally discouraging. According to Meta's 2025 annual filing, its Reality Labs division recorded operating losses of $16.1 billion in 2023, $17.7 billion in 2024 and $19.2 billion in 2025. The three-year total exceeded $53 billion. Those losses encompass Meta's broader virtual- and augmented-reality activities, not simply Horizon Worlds.
The retreat became particularly apparent in March 2026, when Meta initially announced plans to remove Horizon Worlds from its Quest virtual-reality platform and emphasize mobile access. Meta Chief Technology Officer Andrew Bosworth subsequently reversed the VR shutdown decision, preserving existing VR experiences while maintaining mobile as the principal development priority. The distinction matters. Meta did not completely abandon virtual worlds, but it substantially retreated from the notion that immersive VR would soon become the dominant interface for everyday digital life.
The company's financial priorities tell a similar story. Its October 2026 financial disclosures forecast Reality Labs operating losses of $18 billion to $19 billion for the year, while outlining further investment in AI infrastructure and an expected narrowing of Reality Labs losses in 2027 as resources shift toward AI. The metaverse, in other words, was not destroyed by a single technological failure. It was undermined by the absence of a sufficiently compelling reason for ordinary people to change their behavior.
Were NFTs Just Digital Pogs?
NFTs followed a remarkably similar trajectory, although their collapse was driven more directly by speculative excess. A non-fungible token is a unique blockchain-based record that can represent ownership or other rights associated with a particular asset. Unlike interchangeable cryptocurrencies, such as Bitcoin, individual NFTs are distinguishable from one another.
NFTs became enormously fashionable in 2021 and early 2022. Digital artwork sold for millions of dollars, celebrities promoted collectible collections, and investors bought blockchain-linked images, virtual real estate and gaming assets in anticipation of substantial appreciation. Beeple's digital artwork Everydays: The First 5000 Days sold for approximately $69 million at Christie's in March 2021. Collections such as CryptoPunks and Bored Ape Yacht Club became speculative status symbols, attracting celebrities, venture capital and institutional attention.
But the speculative market depended on a questionable proposition: that scarcity created by blockchain records would translate into lasting demand for digital objects. A blockchain can establish that a particular wallet controls a token. It does not automatically confer copyright, exclusive access to the associated image, enforceable legal title to an underlying asset or an economically valuable claim.
Moreover, an NFT's scarcity does not make its associated content scarce. Anyone can generally view or copy the image, even if the underlying token remains unique. When cryptocurrency markets weakened and speculative enthusiasm evaporated, many NFT collections suffered catastrophic price declines. Liquidity disappeared, trading activity contracted and projects that had promised exclusive communities, games or virtual experiences failed to deliver sustainable products.
The resulting collapse should not be confused with the disappearance of NFTs themselves. Some collections retain active communities, certain digital artworks remain valuable, and blockchain-based collectibles continue to trade. However, the proposition that virtually every consumer brand, celebrity and digital creator needed an NFT strategy has been thoroughly discredited.
Fashion companies provide an instructive example. Luxury brands initially viewed NFTs as opportunities to monetize digital scarcity, create exclusive customer experiences and sell virtual apparel. Yet many projects struggled to establish why consumers should pay for blockchain-based versions of goods that offered little additional functionality. The more promising applications involve products in which digital ownership or transferability serves a recognizable purpose, such as transferable game assets, event tickets, membership credentials and certain intellectual-property licensing arrangements.
Even then, blockchain is not necessarily required. A conventional database can manage digital entitlements without exposing customers to cryptocurrency wallets, transaction fees or complicated custody arrangements. That distinction is fundamental: the failure of NFT speculation does not prove that every blockchain-based digital asset is useless. It demonstrates that technological scarcity alone cannot manufacture economic value.
Second Life, a Second Time
The metaverse was not even the first attempt to construct a persistent virtual economy. In 2003, Linden Lab launched Second Life, an online environment in which users could create avatars, build virtual structures, purchase digital land and exchange goods using a virtual currency called the Linden dollar, which was about as useful as Itchy and Scratchy money. Second Life attracted substantial media attention during the mid-2000s. Corporations established virtual offices, universities created digital campuses, and businesses experimented with advertising and commerce inside its simulated world.
For a period, it seemed plausible that consumers would increasingly socialize, shop and conduct business through digital avatars. Instead, mainstream interest faded. Users encountered complicated interfaces, inconsistent performance, awkward navigation and limited practical reasons to substitute a virtual environment for existing websites and communications tools.
Second Life did not disappear, however. It survived as a specialized community with its own creators, merchants and economy. That survival offers an important distinction between technological failure and commercial disappointment. A technology can sustain a viable niche without fulfilling the much grander predictions originally used to justify investment.
The modern metaverse's difficulties therefore were not unprecedented. Zuckerberg's vision repeated many of Second Life's assumptions, supported by better graphics, more sophisticated hardware and vastly larger financial commitments. Neither technological progress nor additional capital resolved the central question: What would convince ordinary users to spend meaningful portions of their lives inside these environments?
Google Glass: An Idea That Really Isn't Dead
Google Glass illustrates another recurring problem in emerging technology: an impressive demonstration does not necessarily translate into a desirable consumer product. Introduced to early users in 2013, Google Glass promised to integrate computing directly into everyday vision through a wearable display, camera and voice-controlled interface.
The technology attracted intense interest because it suggested a future in which smartphones might become unnecessary. Users could receive information, take photographs, navigate and communicate without repeatedly looking at a handheld device. However, Google encountered serious obstacles, including high prices, limited battery life, an underdeveloped application ecosystem and widespread discomfort with wearable cameras. Privacy concerns became especially damaging. Businesses and individuals worried about being recorded without their knowledge, while the device's conspicuous appearance created social resistance.
Google ended the original consumer-focused Glass Explorer program in 2015. An enterprise-oriented successor subsequently targeted specialized industrial applications, including warehouse operations and manufacturing, before Google discontinued Glass Enterprise Edition sales in 2023. The underlying concept nevertheless survived. Smart glasses and augmented-reality devices remain under development by Meta, Google, Apple and other technology companies.
Indeed, AI may improve the commercial prospects of wearable computing by supplying a more compelling purpose: hands-free access to an intelligent assistant capable of interpreting the user's surroundings, answering questions and providing context-sensitive assistance. The lesson is not necessarily that smart glasses were a bad idea. It may be that Google introduced the concept before the hardware, software, social conventions and applications were ready.
Enterprise Blockchain: A Near Miss
Blockchain's enterprise history presents another cautionary tale, particularly for financial services executives. During the late 2010s, banks, insurers, logistics companies and technology vendors launched numerous blockchain initiatives promising to revolutionize recordkeeping, payments, supply chains, identity management and financial transactions. Permissioned blockchains, which restrict participation to approved entities, were especially attractive to businesses seeking distributed records without the unpredictability of public cryptocurrency networks.
However, many projects struggled to demonstrate meaningful advantages over conventional databases and cloud-based infrastructure. One of the most prominent failures was TradeLens, a blockchain-enabled global shipping platform developed by IBM and Danish shipping company A.P. Moller-Maersk. Launched in 2018, TradeLens sought to digitize documentation and coordinate information across shipping companies, ports, customs authorities and logistics providers. In November 2022, IBM and Maersk announced that they would discontinue the platform.
Importantly, Maersk did not attribute the failure to an inability to develop working technology. Instead, it explained that TradeLens had failed to achieve the broad industry collaboration necessary for commercial viability. That explanation identifies a problem shared by many enterprise blockchain projects: distributed systems depend on cooperation among organizations that may have conflicting commercial interests.
A conventional database can be operated by one institution. A shared blockchain may require competitors, regulators, service providers and customers to agree on governance, standards, access rights and operating procedures. Even when technically feasible, the resulting coordination costs can outweigh the benefits. For financial institutions, the question is not whether blockchain can store or verify transactions. It can. The question is whether decentralization produces a measurable advantage over existing systems.
A Second Life for Blockchains?
There are reasons to believe that enterprise blockchain's history may not end with TradeLens. In 2025 and 2026, financial institutions increasingly focused on tokenizing conventional financial assets rather than creating speculative digital collectibles.
The Depository Trust & Clearing Corporation (DTCC), which operates essential U.S. securities market infrastructure, has pursued blockchain-based applications involving securities settlement, collateral management and asset mobility. In July 2026, DTCC announced that its Depository Trust Company subsidiary had successfully used tokenized securities in actual production transactions involving securities lending, collateral pledges, Treasury repurchase agreements and equities. Participating organizations included BlackRock, Goldman Sachs, JPMorgan and other major financial institutions.
Meanwhile, the Bank for International Settlements (BIS) has explored how tokenized central bank reserves, commercial bank deposits and government securities might support more efficient financial infrastructure. Its Project Agorá initiative demonstrated a prototype capable of coordinating cross-border settlement using tokenized commercial bank deposits and central bank reserves. Further testing is necessary before its benefits can be established at commercial scale.
These initiatives differ from speculative NFT markets because they target identifiable operational problems: settlement delays, fragmented records, collateral inefficiencies and complicated reconciliation processes. Nevertheless, their commercial success remains uncertain. As a BIS-related discussion published in October 2026 emphasizes, tokenization's benefits depend heavily on interoperability, institutional coordination and the participation of financial market infrastructure providers.
The distinction is particularly relevant to financial advisors and wealth managers. Tokenized securities might eventually support more efficient settlement, fractional ownership, automated compliance and improved portfolio administration. But those benefits depend on enforceable legal rights, reliable custody arrangements, market liquidity and regulatory compliance—not simply the existence of a blockchain. The technology may succeed precisely because financial institutions are abandoning the more extravagant promises of the original blockchain boom.
Is AI Another Metaverse?
The parallels between AI and earlier technology bubbles are impossible to dismiss. Like the metaverse, AI has attracted enormous corporate investment, sweeping predictions about economic transformation and pressure on executives to adopt unfamiliar technologies before competitors do. Companies routinely describe AI as indispensable to their future competitiveness. Venture capital investors have financed businesses with limited revenues, and public-market valuations increasingly depend on assumptions about future AI demand.
There are also concerns that the infrastructure buildout is running ahead of demonstrated economic returns. Reuters reported in July 2026 that capital expenditures by Microsoft, Alphabet, Amazon, Meta and Oracle were placing growing pressure on free cash flow. Its analysis of financial estimates suggested that the companies' combined capital spending could exceed their free cash flow by 2027.
Meta provides a particularly striking illustration of the industry's shifting priorities. After committing tens of billions of dollars to immersive computing, it has redirected attention toward AI. Its latest October 2026 financial outlook anticipates capital expenditures of $135 billion to $145 billion for 2026, primarily reflecting an infrastructure strategy increasingly focused on artificial intelligence.
The pattern resembles previous technology booms: executives identify a potentially transformative platform, investors extrapolate rapid adoption, and corporations spend enormous sums establishing infrastructure before long-term demand becomes clear. Yet AI possesses one important advantage over the metaverse and speculative NFTs. People are already using it to accomplish tasks they previously performed without AI.
Unlike virtual offices or digital collectibles, generative AI can produce useful outputs without requiring consumers to purchase specialized hardware, adopt a new digital currency or participate in an unfamiliar virtual economy. AI tools can draft correspondence, summarize documents, generate software, analyze information, translate languages and automate routine business processes. Financial institutions can apply these capabilities to compliance reviews, fraud detection, customer service, document processing, investment research and financial planning. The difference is measurable.
According to Stanford University's 2026 AI Index Report, 88% of surveyed organizations reported using AI in at least one business function in 2025, compared with 78% in 2024. The report also identified productivity improvements in specific applications, including customer support, software development and marketing, although results vary significantly by task and implementation. These findings distinguish AI from technologies that never established substantial mainstream demand. They do not, however, prove that current AI valuations or capital expenditures are justified.
A technology can be useful and still become the subject of a financial bubble. The internet transformed commerce, communication and finance, but that did not prevent the dot-com crash from destroying enormous amounts of investor capital. Many internet companies failed even as the underlying technology became essential. AI could follow a similar path. Its economic utility may be genuine, while particular companies, business models and infrastructure investments prove financially unsustainable.
Future's Cost
The most consequential similarity between AI and the metaverse may be the financial commitments made before the ultimate market opportunity is understood. Meta's metaverse investments were expensive, but AI infrastructure demands potentially much larger expenditures across the technology industry. Training and operating sophisticated AI models require specialized processors, networking equipment, cooling systems, electricity, data centers and substantial engineering resources.
Unlike a failed consumer application that can be discontinued relatively cheaply, large infrastructure projects create long-lived financial obligations. Data centers may require years of planning and construction. Electricity contracts and financing arrangements can extend well beyond the period during which today's AI models remain competitive.
Meanwhile, technological improvements may reduce the computing resources required to accomplish particular tasks, potentially weakening the economics of infrastructure built around earlier assumptions. Greater efficiency could also increase total demand by making AI applications cheaper and more widely accessible. Both outcomes are plausible, making capacity planning especially difficult. This creates several risks for investors. Companies may overestimate demand, underestimate operating expenses, face faster-than-expected hardware obsolescence or struggle to convert user adoption into profitable revenue.
Financial institutions face a parallel challenge when purchasing AI services. A bank may successfully demonstrate that a model can summarize loan documents or answer customer questions, only to discover that production deployment requires expensive security controls, human oversight, systems integration and regulatory compliance. The critical metric is not how impressive the model appears during a demonstration. It is whether the application delivers a sustainable economic benefit after all relevant costs are included.
Can AI Resurrect Dead and Dying Techs?
Ironically, artificial intelligence may improve the prospects of some technologies it has displaced in the public imagination.
Generative AI can reduce the cost of creating virtual environments, producing three-dimensional objects and animating digital characters. AI-powered non-player characters could make virtual worlds more engaging, while conversational assistants might allow users to interact with immersive environments without mastering complicated controls. The combination could make virtual training, education, simulation and entertainment more practical.
AI could also improve augmented-reality applications by interpreting physical surroundings and delivering useful information in real time. For example, an insurance adjuster might use smart glasses to document property damage, while an industrial technician could receive equipment diagnostics through an augmented display. Financial advisors might eventually use immersive visualization tools to explain retirement outcomes, portfolio risks or complex financial products.
But none of these applications necessarily requires a metaverse.
Likewise, combining NFTs with AI-generated characters or evolving digital artwork does not automatically create economic value. So-called intelligent NFTs may offer novel entertainment experiences, but blockchain ownership contributes little unless the user benefits from verifiable transferability, provenance or enforceable rights.
The most plausible future is one in which AI, augmented reality and blockchain survive as distinct technologies, occasionally intersecting where their combined capabilities solve specific problems. The grand vision of an interconnected virtual economy may never materialize. Individual applications, however, could succeed without it.
Spotting the Phonies
How can investors identify the next technological failure? For financial professionals, the history of NFTs, the metaverse, enterprise blockchain, Google Glass and 3D television suggests several recurring warning signs.
The first is a technology being promoted primarily for its capabilities rather than the problems it solves. When advocates struggle to explain why customers need a product, extravagant forecasts should invite skepticism.
The second is excessive friction. Products that require unfamiliar hardware, complicated procedures, behavioral changes or substantial additional expenses must deliver correspondingly large benefits.
Third, investors should distinguish genuine adoption from speculative participation. NFT trading activity, for example, was not equivalent to sustainable demand for blockchain-based ownership. Similarly, AI chatbot usage does not necessarily translate into profitable enterprise software subscriptions.
Fourth, companies should evaluate whether simpler alternatives accomplish the same objectives. Blockchain applications should be compared with conventional databases; virtual collaboration environments with videoconferencing; and AI agents with traditional automation.
Fifth, executives should examine unit economics, including customer acquisition costs, recurring expenses, retention, infrastructure requirements and the amount of human intervention necessary to deliver promised results.
Finally, financial institutions should consider whether the technology's benefits depend on coordinated adoption across an entire industry. Such dependence can make even technically successful systems commercially impractical. These principles are especially important for wealth managers evaluating AI vendors, technology-themed investments and emerging digital assets. Financial advisors should distinguish between investing in a promising technology and investing in a company capable of capturing the economic value that technology creates.
The future belongs to useful technology, not necessarily fashionable technology
The metaverse and NFTs offer cautionary examples of what happens when technological enthusiasm becomes detached from customer needs and economic fundamentals. Enterprise blockchain, Second Life, Google Glass and 3D television demonstrate that the consequences need not be absolute failure: technologies can retreat into specialized markets, evolve into different products or eventually find viable applications.
Artificial intelligence is unlikely to disappear in the manner of a short-lived consumer fad. Its existing applications, measurable productivity benefits and widespread adoption provide a stronger foundation than the speculative narratives that sustained many earlier technology booms. But its utility does not immunize investors from excessive valuations, infrastructure overbuilding or disappointing financial returns. The most important lesson for financial services executives is that technological progress and investment success are not interchangeable. A technology can change the world while destroying the capital of investors who paid too much, backed the wrong companies or arrived before the market was ready. The winners will not necessarily be those who make the boldest predictions about the future, but those who can demonstrate that their products solve real problems at a cost customers are willing to pay.
Researched by DWN Staff